Burning hot refiners
One standout strong performer has been refiners, a theme we wrote up in late 2025 and revisited in February of this year, just before Trump and the Iranians lit a fire under this trade. In short, crack spreads are burning hot right now.

Depending on which CEO you listen to, around 5-7m bpd of refining capacity is currently offline, excluding normal maintenance downtime. US gasoline inventories are well below their 5-year range, and distillates are at the bottom of their 5-year range.
US refiners are running flat out, deferring maintenance for as long as possible to cash in on the current bonanza.
Want to just cut through the noise and get actionable event-driven ideas?
KEDM Lite is a must for event-driven investors.

Each weekly issue of Lite delivers:
- 30+ actionable special situations and event-driven ideas (42–46 issues per year)
- Deeper focus on small and mid-caps, where alpha often hides
- Happy Hour webinars with our own Kuppy and guests, plus AMA sessions
- Full Lite archive access, growing into thousands of highlights over time
*Early subscribers to the annual plan will get access to the KEDM Discord room. All KEDM Pro subscribers get Lite for free!
Kliff Note of the Week
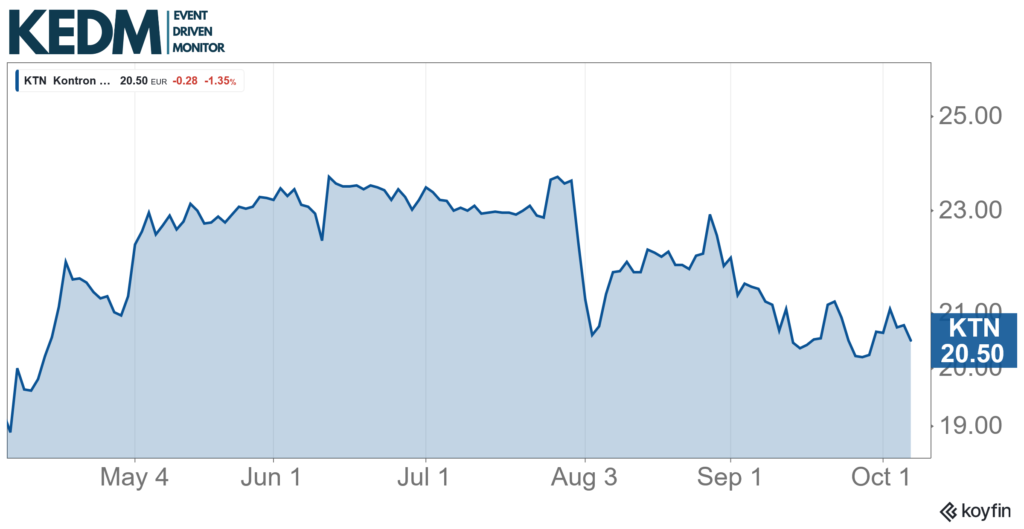
Cluster Buying Notes: Kontron’s (KTN GR) CEO and Chairman continues to buy shares relentlessly on the open market. Kontron recently held a CMD, keeping its 2030 goals unchanged; this is €2.6bn revenue and €420m EBITDA, the latter a ~20% 2026-2030 CAGR.
Ennoconn’s stake has now risen to 48%, and dividends will restart again, rising toward €1.50 by 2030 (~7% yield on today’s price). We should see FCF ramping again going forward. 8x forward EV/EBITDA. We get why the CEO is buying.
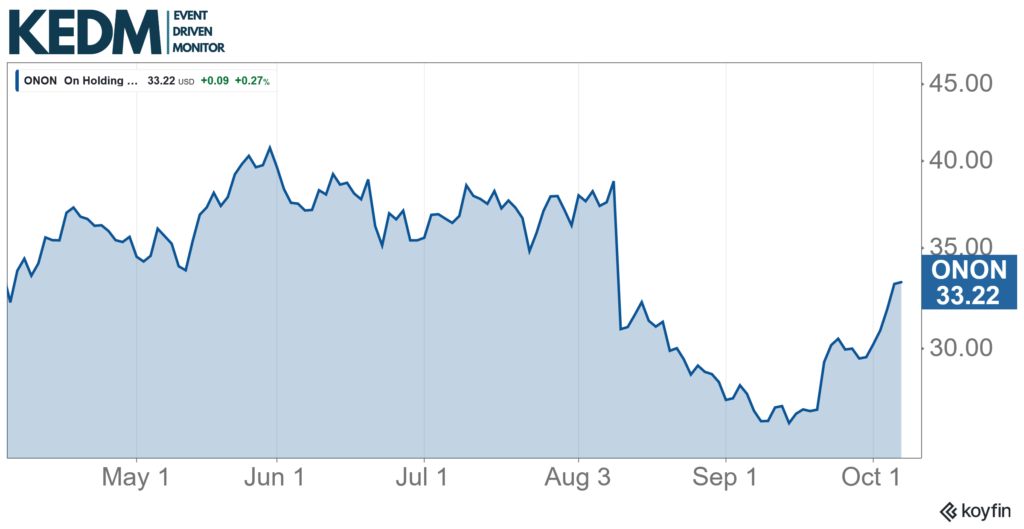
Buyback Notes: Good timing seems to be on our recent On Holding (ONON) flag. On laid out solid mid‑term financial targets (at least CHF5.6bn 2029 sales and high‑teens cc growth over the medium term) and approved a $1bn buyback running through December 2029.
That’s ~10% of the current market cap. Shares have derated strongly over the past months. Major insider-buying-the-dip name.
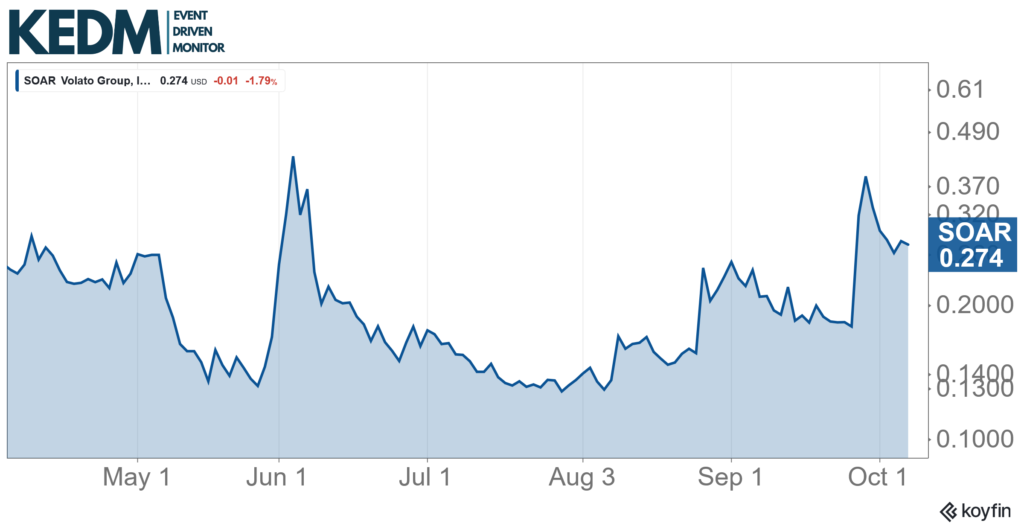
CEO Golden Handcuffs Notes: Volato (SOAR), a private-aviation company, has been expanding into AI infrastructure. Alignment Engine’s former CEO, Christopher Ensey, was appointed CEO as an independent contractor based in Puerto Rico, with a $400k annual services fee.
Ensey will get restricted stock equal to 5% of Volato’s fully diluted cap. The award would vest in five 1% tranches, tied to specific market cap thresholds and corresponding contracted-capacity milestones: $2.5bn and 63MW, $4.2bn and 105MW, $7bn and 175MW, $11bn and 275MW, and $17bn and 400MW.
Contracted capacity means either a signed non-cancellable customer contract or delivered capacity. Upon a change in control, this is the binding constraint for unvested tranches.
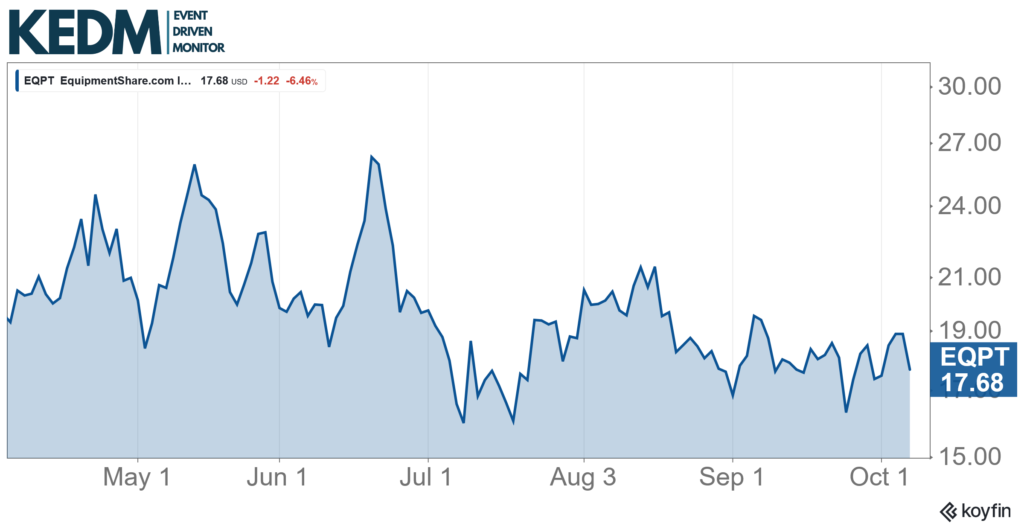
Newsletter Short Notes: Busted IPO Equipmentshare.com (EQPT) was supposed to be a capital-light alternative to equipment rental companies such as URI and AHT, where independent 3rd parties own the equipment to capture accelerated depreciation while EQPT operates it.
In a short report, Blue Orca claims it isn’t what it seems, arguing that EQPT has off-balance-sheet minimum value guarantees and questioning whether those 3rd parties are truly independent. They also flag the dumping of shares by large shareholder Romulus Capital after the recent unlock.
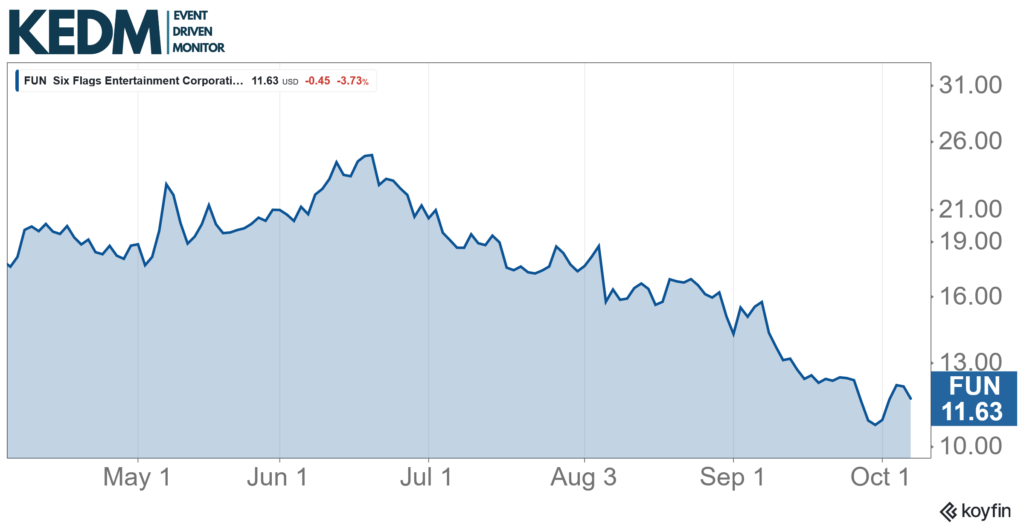
13D and Activist Notes: Jana Partners is again pushing Six Flags (FUN) to explore a sale, clearly frustrated with weak performance and slow turnaround progress. The activist wants the board to run a formal strategic review asap.
FUN’s latest quarter showed 7% declines in revenue and attendance, and the stock is down ~45% over the past year. Six Flags has already replaced its CEO, sold seven non‑core parks ($331m), and is dealing with new roller‑coaster injury lawsuits.
Disclaimer. KEDM is provided for informative purposes only. No due diligence has (yet) been performed on the names on this list. The list might change strongly on a regular basis. This overview does not constitute advice; always do your own due diligence. For the full disclaimer, please go here.