The bigger picture
While the market worries about stablecoins disrupting Remitly and Wise, both continue to take share from legacy players like Western Union and MoneyGram.
In the legacy model, Western Union earned fat take rates partly because the payment rails included a bodega taking your cash in New York and another handing it to your aunt in New Delhi. Both took a cut, making much of the cost base variable.
Today, the rails are largely technology, plus the occasional bodega when grandma in the Philippines doesn’t have a bank account. Technology is mostly a fixed cost, creating economies of scale and room for fewer winners.

With take rates falling from 5%+ to barely 2%, the real costs, and increasingly the competitive advantage, have shifted to customer acquisition, AML/KYC, and fraud. The rails themselves matter less.
That’s why stablecoins don’t necessarily cannibalize RELY. If they provide a cheaper rail, RELY can simply use it. And management says they already do, “where it makes sense.”
Ask them about stablecoins, and you’ll quickly end up discussing the cost of converting USDC into Peruvian soles so grandma can buy an Inca Kola. The blockchain is fantastic right up until grandma wants soles instead of USDC.
Want to just cut through the noise and get actionable event-driven ideas?
KEDM Lite is a must for event-driven investors.

Each weekly issue of Lite delivers:
- 30+ actionable special situations and event-driven ideas (42–46 issues per year)
- Deeper focus on small and mid-caps, where alpha often hides
- Happy Hour webinars with our own Kuppy and guests, plus AMA sessions
- Full Lite archive access, growing into thousands of highlights over time
*Early subscribers to the annual plan will get access to the KEDM Discord room. All KEDM Pro subscribers get Lite for free!
Kliff Note of the Week
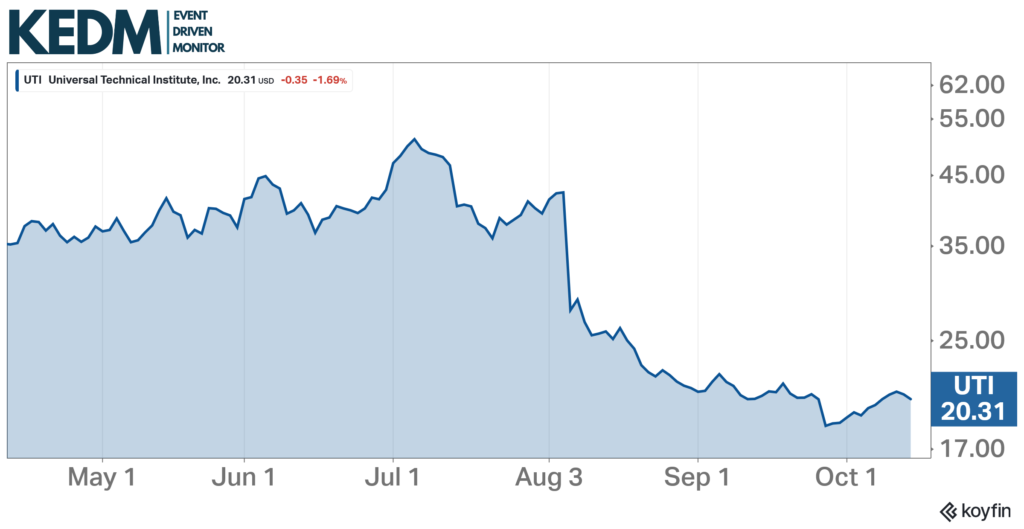
Cluster Buying Notes: Flagging insider purchases at Universal Technical Institute (UTI), where a director has consistently added shares in the open market during the recent hurt. This guy is a smart cookie, and we love seeing him add.
Pressure on UTI continues, as there are clearly no buyers for a company that might need more than 1 quarter to right the ship. Please see our write-up on the industry’s LLM search problems from last week.
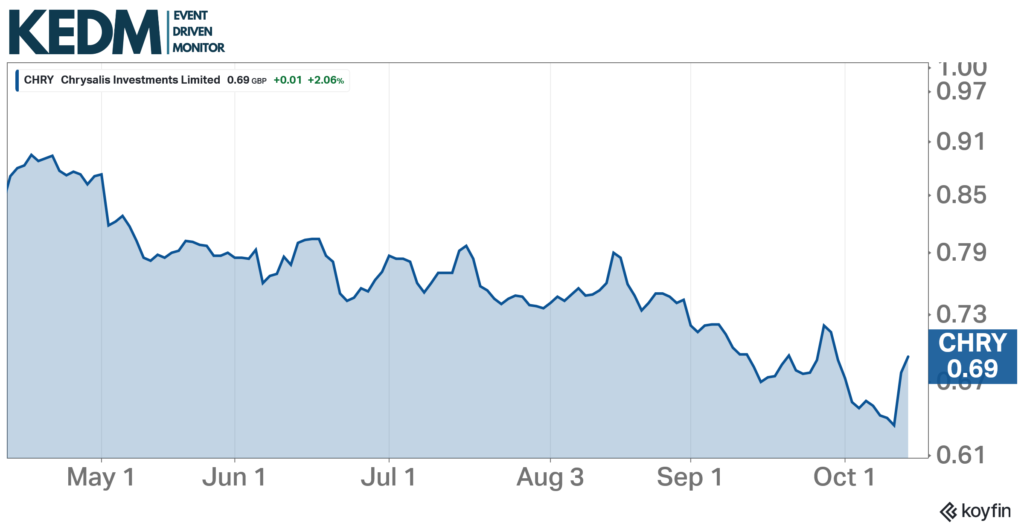
Buyback Notes: Chrysalis Investments (CHRY LN) will return ~£25m to shareholders after finally fully exiting its Klarna stake. This is done at 127p p/s via a compulsory redemption.
They trust will keep £9m for liquidity, leaving ~£19m cash on hand. Klarna has been a major drag (NY listing collapsed >70%) and CHRY recently also corrected a £16m ‘valuation error’ related to its Wefox investment and the dismissal of its portfolio managers.
Chrysalis is currently in a three‑year wind‑down. The latest NAV was 131.1p p/s vs a 67.5p share price today.
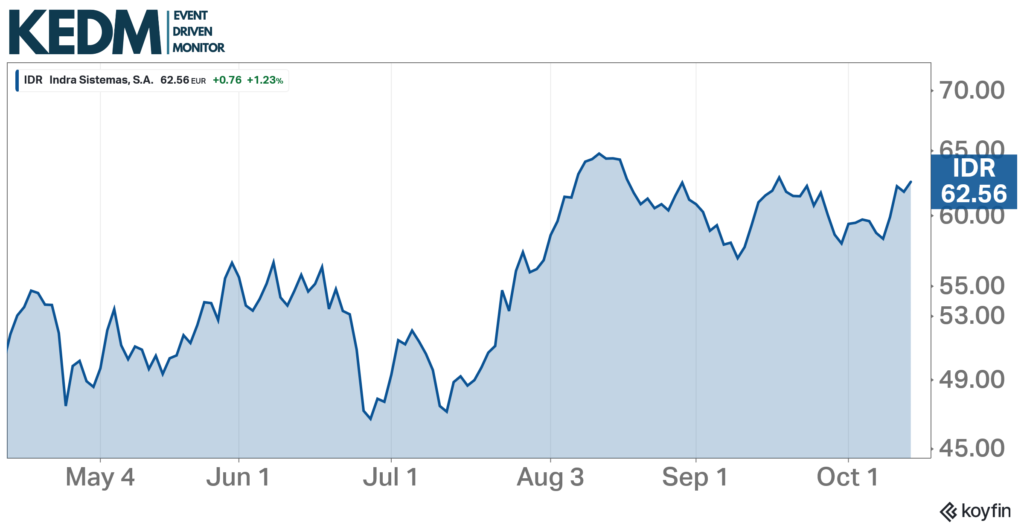
Investor Day Notes: Interesting moves from Spanish IT consultant Indra Sistemas (IDR SM). The company is carrying out some major management reshuffles ahead of its big Nov. 25 CMD, shrinking the board to 10 members and consolidating some responsibilities.
Five senior executives have been kicked out, including the CTO and CSO. When reading this, you might think this company has done terribly, but to the contrary – shares are close to ATHs.
Indra is a large winner of increased Euro defense and space budgets, with much more to come. Still ~10x forward EV/EBITDA for what should be 15-20% EBITDA growth p.a. over the medium-term.
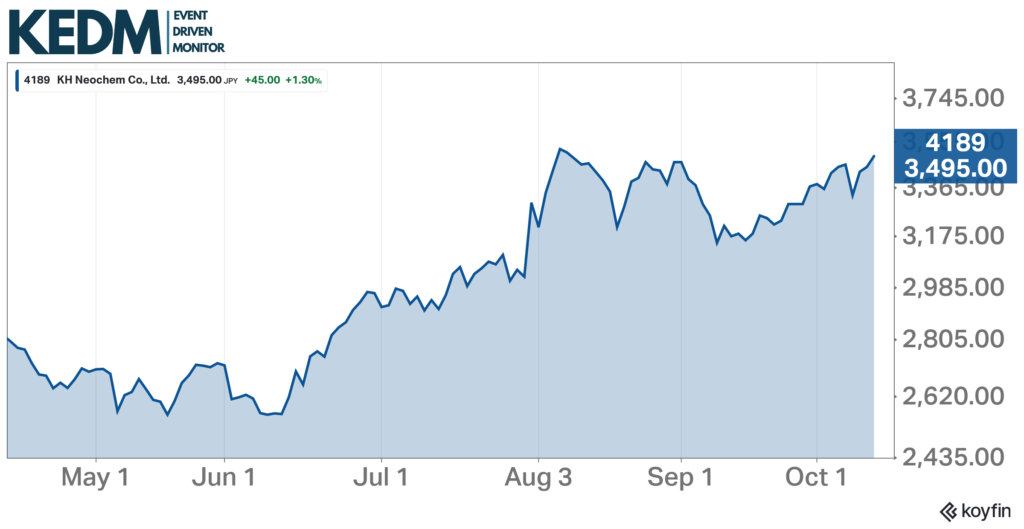
Japanese Activism Notes: KH Neochem (4189 JP) recently raised its dividend payout target from 40% to 50% and DOE from 4% to 5%. Yet activist shareholder Strategic Capital, which owns 18.24%, has escalated its campaign by explicitly demanding a 100% dividend payout ratio (7.3% yield), alongside broader capital-allocation and portfolio-restructuring proposals.
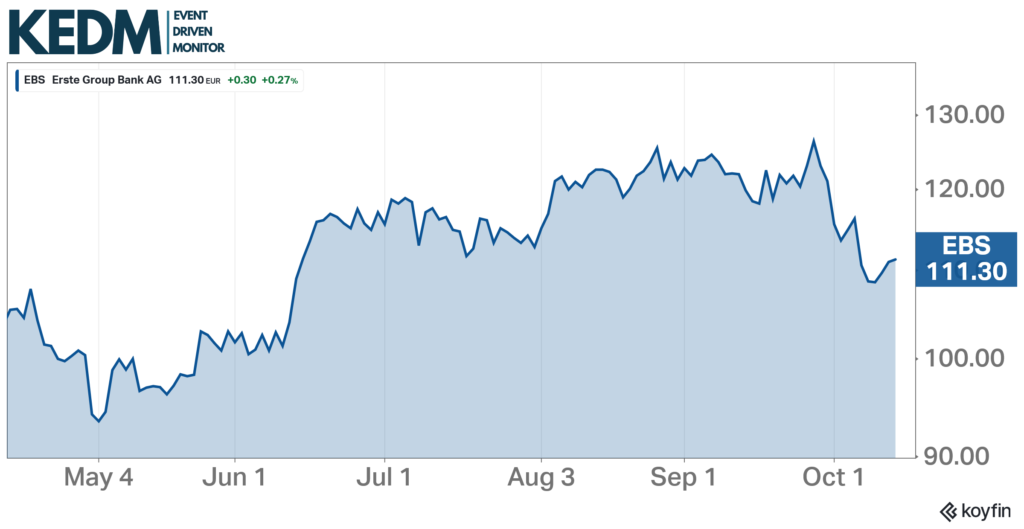
Tender Offer Notes: Erste Group Bank (EBS AV) is launching a tender offer at PLN 713 p/s to lift its stake in Erste Bank Polska (EBP PW) from 49% up to as much as 75%. The deal only works if acceptances push Erste above 50%, regulators approve, and at least 25% free float remains.
The price is 22% above what Erste paid in January but way below the current market price (roughly PLN 775), so reaching 75% is tough. Higher bid incoming? EBP is a strong Polish bank with healthy corporate loan growth.
Disclaimer. KEDM is provided for informative purposes only. No due diligence has (yet) been performed on the names on this list. The list might change strongly on a regular basis. This overview does not constitute advice; always do your own due diligence. For the full disclaimer, please go here.